
What Are Defined-Risk Market-Neutral Spreads?
Defined-risk market-neutral spreads are four-leg options orders designed to profit from time decay and declining implied volatility while keeping maximum potential loss strictly capped. By combining a bull put spread below the current asset price with a bear call spread above it, traders establish a trade structure that generates a net credit upon entry without requiring a directional bias.
Both iron condors and iron butterflies belong to this defined-risk credit spread family. Each leg consists of a long option contract that acts as a protective "wing" against severe market gapping. Because the outer wings cap margin requirements, these setups are far safer for account equity than unhedged short straddles or short strangles.
An iron condor uses out-of-the-money short options to create a wide plateau profit zone, while an iron butterfly uses at-the-money short options to collect higher upfront credit across a narrower, triangular profit range.
Understanding how multi-leg positions operate is foundational to advanced options trading. While traditional credit spreads utilize only two legs to capture directional movement, market-neutral structures utilize four contracts simultaneously to benefit when an asset consolidates within an expected price channel.
It is important to distinguish a standard condor vs iron condor. A traditional condor spread is constructed entirely with options of a single type—either four calls or four puts—and typically requires paying a net debit. In contrast, an iron condor combines two calls and two puts to generate an initial credit. This initial credit reduces the capital required to hold the trade, making iron multi-leg structures preferred for income-oriented strategies.
How Option Strikes Shape the Payoff Structure: ATM vs. OTM Mechanics
Strike placement dictates whether a neutral options setup produces a wide profit plateau or a concentrated profit peak. The fundamental structural distinction in an iron condor vs butterfly setup comes down to where the short option contracts are sold relative to the current market price of the underlying asset.
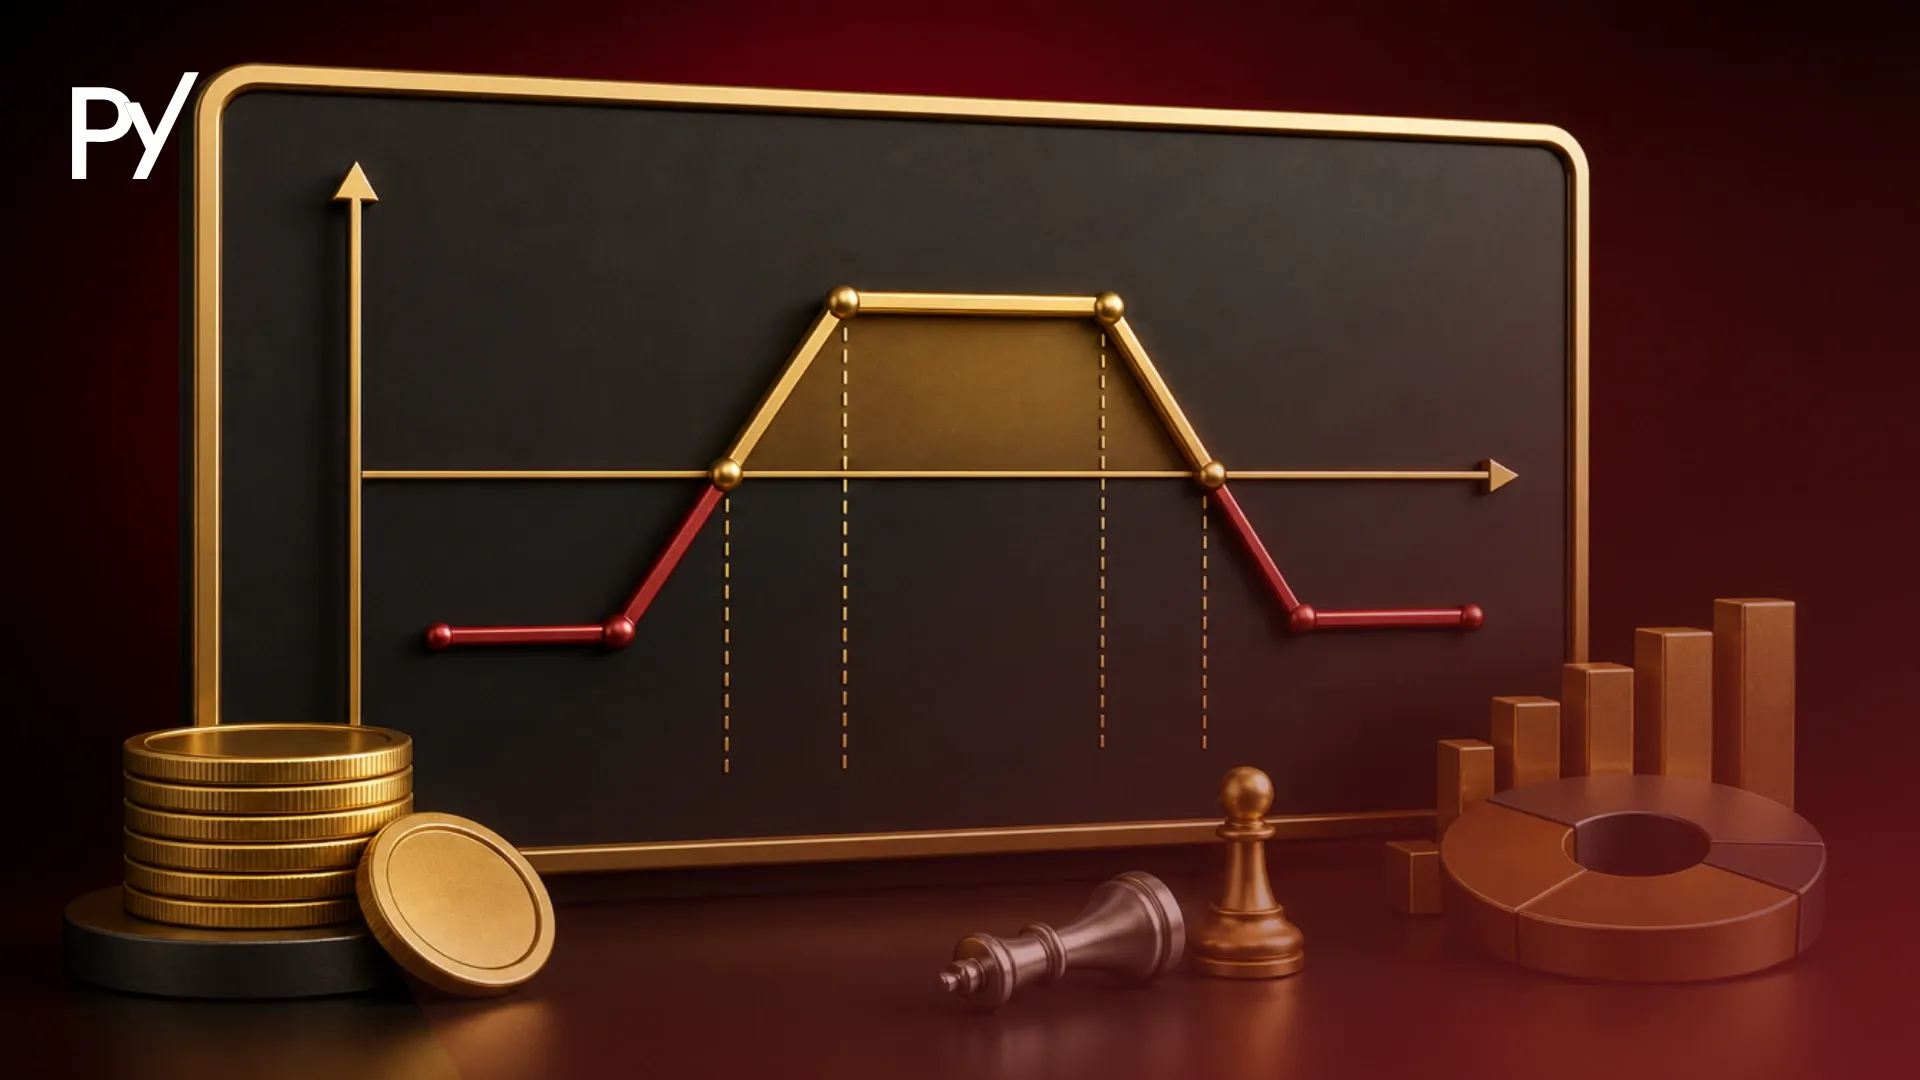
In an iron condor, you sell an OTM short put below the current market price and an OTM short call above it. You then purchase a further OTM put and a further OTM call to define your maximum loss boundaries. This arrangement leaves a wide "profit zone" between the two short strikes. As long as the underlying asset stays between these two short boundaries through expiration, all four options expire worthless, allowing you to keep 100% of the initial credit collected.
In an iron butterfly, you sell an ATM short put and an ATM short call at the exact same strike price (or as close to the spot price as possible). You then purchase an OTM put below and an OTM call above to serve as outer protective wings. Because ATM options contain the highest amount of extrinsic value (time premium), selling them yields a significantly larger upfront credit than selling OTM contracts.
The net credit collected on an iron butterfly is typically much larger than on a comparable iron condor.
However, this higher credit comes at a cost. The iron butterfly's payoff diagram resembles a sharp triangle rather than a flat plateau: profit is highest right at the center ATM strike and narrows quickly as price moves away in either direction. By contrast, the iron condor's payoff stays flat across a wide plateau between its two short strikes before dropping off toward the wings. To capture maximum profit on the butterfly, the underlying asset must close exactly at the center ATM short strike at expiration. As price strays away from this center point in either direction, unrealized gains diminish quickly.
Traders transitioning from stock replacement methods—such as a poor man's covered call strategy—often struggle with this dynamic. Debit strategies rely on directional expansion, whereas both iron structures rely on time decay (Theta) and price containment.
Iron Condor vs Iron Butterfly: Key Differences Compared
Selecting between an iron condor vs iron butterfly requires analyzing the trade-off between win rate probability and risk-to-reward metrics. Neither structure is universally superior; each excels under different market conditions and volatility environments.
| Metric / Parameter | Iron Condor | Iron Butterfly |
|---|---|---|
| Short Strike Selection | Out-of-the-Money (OTM) Call & Put | At-the-Money (ATM) Call & Put |
| Payoff Geometry | Trapezoidal / Flat Plateau | Triangular / Sharp Peak |
| Upfront Net Credit | Moderate (15% – 30% of wing width) | High (40% – 60% of wing width) |
| Max Loss Potential | High relative to credit collected | Low relative to credit collected |
| Probability of Profit (POP) | High (60% – 80%) | Lower (35% – 50%) |
| Breakeven Range | Wide (Far from current spot price) | Narrow (Close to current spot price) |
| Vega Sensitivity | Moderate short Vega | High short Vega |
An iron condor provides a wider margin for error. Because your breakeven points sit far beyond the underlying asset's expected move, the price can fluctuate significantly without threatening the position. However, because the upfront credit collected is smaller, the maximum potential loss on a tested wing is higher relative to the profit target:
Max Loss = Wing Width − Credit Received
Conversely, an iron butterfly offers an attractive risk-reward profile. Collecting a large upfront credit naturally expands your breakeven points outward from the ATM strike, even though the peak profit region remains narrow. If the underlying asset stays within a moderate range, an iron butterfly can generate rapid profits—especially if implied volatility falls steeply.
Choosing between these two neutral options strategies often comes down to balancing probability against yield. Funded traders who prioritize a high win rate frequently favor the iron condor, whereas those targeting maximum credit per dollar of wing risk gravitate toward the iron butterfly.
Implied Volatility and Vega Sensitivity
Both trades are short Vega positions, meaning they benefit when Implied Volatility (IV) contracts. However, because ATM options contain the maximum extrinsic value, an iron butterfly carries a substantially higher short Vega exposure than an iron condor.
When Implied Volatility Rank (IVR) is elevated (above 50), entering an iron butterfly allows you to sell overinflated ATM premium. If IV collapses following an earnings release or economic announcement, the extrinsic value of the ATM options drops rapidly. This lets you close the trade for an early profit even if the stock has moved slightly away from the center strike.
Managing Risk in Funded Accounts: Drawdown Locks and Pin Risk
Executing multi-leg credit strategies inside a funded trading account requires strict attention to firm-specific operational constraints. Operating through a what is a prop firm structure introduces strict daily drawdown limits and trailing equity limits that directly impact how options positions must be sized and managed.
Daily Drawdown and Max Wing Width
In a prop account, your maximum risk on a trade is not merely defined by the contract rules—it is constrained by the firm's daily drawdown rule. Consider the following scenario:
- Starting Account Balance: $100,000
- Max Permitted Daily Drawdown (5%): $5,000
- Position: 10 contracts at a $7.50 wing width = $7,500 max theoretical loss
Here, the max trade loss ($7,500) exceeds the daily drawdown limit ($5,000). A sudden gap through the outer wings on this position would breach the account's rules before the trade could be managed.
If your funded account allows a maximum daily loss of $5,000, a sudden overnight gap that pushes the asset beyond your protective outer wings will trigger an automated account violation.
To keep your account safe, calculate your total position max loss so that it never exceeds 25% to 30% of your daily drawdown limit:
Position Max Loss ≤ Daily Drawdown Limit × 0.30
Pin Risk and Expiration Traps
Another hazard when trading multi-leg spreads near expiration is "pin risk." This occurs when the underlying asset price closes directly on or extremely close to one of your short options strikes on expiration Friday.
If the asset closes right at your short call strike, you face uncertainty over whether the option buyer will exercise their contract. If assigned after market close, you could wake up on Monday holding a short stock position without the protective long call (which expired worthless). In a funded trading account, holding unhedged overnight stock equity can cause immediate liquidation or account closure due to leverage and margin violations.
To eliminate pin risk, close all multi-leg credit positions at least 24 to 48 hours prior to expiration, or whenever the underlying price gets uncomfortably close to a short strike during expiration week.
Common Execution Mistakes and Volatility Traps
Even experienced market-neutral options traders run into execution traps when market conditions change rapidly. Avoiding these three common mistakes will help protect your trading capital:
- Holding Positions into Expiration Week: As expiration approaches, option decay (Theta) accelerates, but so does directional risk (Gamma). A small price move late in the cycle can cause rapid swings in unrealized loss. Close trades at 25% to 50% of maximum profit to free up margin and reduce exposure.
- Trading Iron Butterflies in Low Volatility Environments: Entering an iron butterfly when Implied Volatility Rank (IVR) is below 20 is inefficient. In low-IV environments, the credit collected is smaller and the breakeven points sit closer to the center strike, leaving little room for price movement.
- Sizing Positions Based on Margin Instead of Max Loss: Brokerage platforms often display initial margin requirements rather than potential tail-risk loss. Always size your trades based on the worst-case scenario (Wing Width − Credit Collected) relative to your account drawdown thresholds.
Conclusion
Choosing between an iron condor and an iron butterfly comes down to market volatility and your risk tolerance. The iron condor provides a wider profit zone and higher probability of success at the cost of a lower reward-to-risk ratio. The iron butterfly offers maximum credit and lower capital at risk, but requires precise market timing and an environment with contracting volatility. For funded traders managing strict daily and trailing drawdown limits, matching the right spread mechanics to current market conditions is essential for long-term consistency.